UNest: Invest & Save for Kids

Screenshots
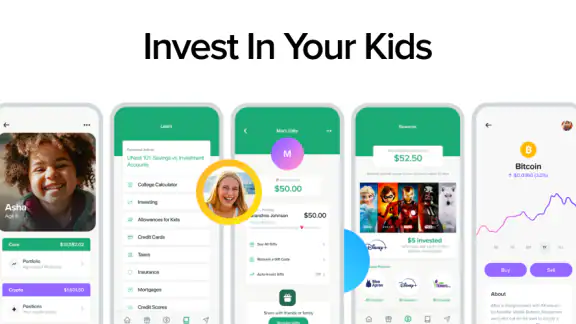
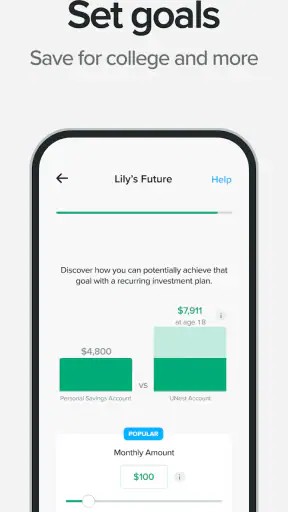
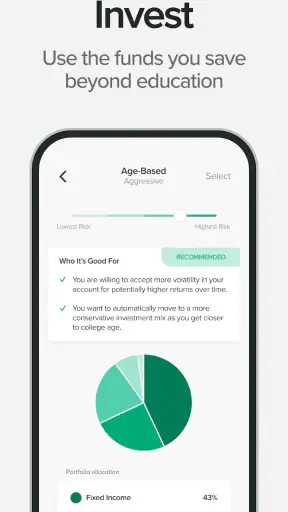
Details
- Rating
- 430.00 reviews
- Version
- 3.8.1
- Developer
- UNest Holdings, Inc.
Analysis by Norviv
Saving for a child is easy to postpone because the goal feels distant and the choices can become confusing quickly. UNest takes a more focused approach: it is a finance app built around saving and investing for children through a UTMA custodial account. I found its appeal less in offering a broad collection of financial tools and more in putting one family goal at the center of the experience.
That focus makes it easier to understand what the app is for. You are not opening it to manage every part of your financial life, trade actively, or replace a full banking app. You are using it to create a dedicated path toward money set aside for a child. The app is free to download, although in-app purchases range from $4.99 to $149.99 per item, so I would look carefully at any paid option before committing.
UNest Holdings, Inc. developed the app, which carries an Everyone age rating. It was released on November 27, 2019, and the current version is 3.8.1. The Android listing shows a minimum requirement of Android 7.0, making it accessible to many older devices, at least from an operating-system perspective.
How UNest feels during everyday use
In everyday use, I’d treat UNest as a place to make deliberate check-ins rather than something to monitor constantly. A helpful habit is to decide what you want to verify before opening it—such as whether a contribution is reflected or whether the account still matches your family’s goal—so each visit has a clear purpose and doesn’t turn into impulse-driven tinkering.
A focused starting point for a long-term goal
The strongest part of the experience is the narrow purpose. When an app is designed specifically around children’s savings, the first question is usually clearer: what am I setting aside, for whom, and why? That is more approachable than opening a general investment platform filled with charts, account types, market terminology, and unrelated tools.
The UTMA structure is important here. A custodial account is not simply a labeled savings jar inside an ordinary banking app. It involves an adult managing assets for a child, so I would treat the account setup as a decision that deserves attention rather than something to rush through. The app can make the process feel more approachable, but it does not remove the responsibility of understanding who controls the account and how the money is intended to be used.
For a parent who has repeatedly said, “I should start saving for my child,” a dedicated app can provide useful psychological separation. The money has a defined purpose instead of disappearing into a general balance. That separation is one of the less obvious strengths of UNest: the app’s value may come as much from keeping the goal visible as from the investment component itself.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
Speed expectations and the feeling of control
In my experience with finance apps, perceived speed matters most during short actions: opening the account area, checking progress, reviewing a contribution, or confirming that a change was accepted. UNest is best approached as a planning and monitoring tool rather than an app for constant activity. Its purpose does not require the rapid, transaction-heavy rhythm of a trading platform.
That distinction helps set realistic expectations. A long-term custodial account should not be judged by the same standard as a payment wallet, where every tap is expected to produce an immediate result. The useful question is whether the app lets you move through important decisions without unnecessary confusion. For this kind of product, clear confirmation and understandable account information matter more than flashy motion or an abundance of live market panels.
I also would not treat a smooth opening screen as proof that every financial action is instantaneous. Investment-related activity can involve steps outside the visual interface, and users should allow time for account processes rather than repeatedly tapping when something does not appear immediately. That is a practical habit with UNest: submit one action, read the confirmation carefully, then check again later instead of assuming that repeated attempts will make it faster.
What happens during heavier use
UNest is not a resource-heavy entertainment app. The typical session is likely to involve reading account information, reviewing a goal, making a contribution, or checking settings. That means it should be less demanding than apps that constantly stream video, render complex graphics, or track location in the background. On a reasonably maintained phone, I would expect the basic experience to feel manageable rather than burdensome.
The heavier moments are more likely to come from attention than from processing power. Setting up a custodial account requires careful reading, and reviewing investment choices can take longer than checking a bank balance. If you are using the app while distracted, the risk is not merely that a screen takes a moment to load; it is that you may skim an important choice because you are trying to finish quickly.
A useful workflow is to separate setup from routine maintenance. I would choose a quiet moment for the initial account work, decide how the child’s goal fits into the household budget, and then use shorter sessions for later checks. This makes the app feel lighter and reduces the temptation to make a financial decision while multitasking.
Stability, recovery, and cautious habits
Financial apps earn trust through consistency. I want the account view to open predictably, the information to be legible, and completed actions to be distinguishable from actions still waiting for attention. UNest’s focused design is helpful in that respect because there are fewer reasons to wander through unrelated sections.
Still, no app should be the only place where you remember what you intended to do. Before making a contribution or changing a plan, I recommend keeping a simple personal note about the amount, the child’s goal, and the date you acted. That is not a criticism unique to UNest; it is sensible recovery planning for any financial service. If the app closes, the connection drops, or you are unsure whether a screen refreshed, your own record gives you a reference point.
When something appears stuck, the safest recovery process is deliberately boring: avoid submitting the same request repeatedly, close and reopen the app, check whether the account view reflects the action, and review any confirmation message. If the result still looks unclear, contact the relevant support channel before trying again. In finance, caution is more valuable than forcing a quick result.
Older devices and practical constraints
The Android requirement of 7.0 is modest, which is good news for people who keep a phone for several years. It does not guarantee identical performance across every device, however. An older phone may have limited free storage, a crowded background workload, or a slower connection, and those factors can affect how responsive any account app feels.
I would keep the operating system updated when the device supports it, leave enough free storage for normal app operation, and avoid making an important account change while using an unreliable connection. These are simple precautions, but they matter more in a financial app than they do in a casual game because uncertainty about whether an action completed can create unnecessary stress.
The minimum operating-system requirement also helps explain who may need to look elsewhere. If you use an iPhone, the relevant installation experience will depend on the iOS version supported by the available release, while this particular requirement describes Android. Families sharing older devices should check compatibility on the appropriate platform before planning around the app.
A realistic family scenario
Imagine a parent who receives irregular income and wants to save for a child without mixing that money with monthly spending. Instead of promising a large amount and abandoning the plan after an expensive month, the parent could use UNest as a dedicated place to review the goal and contribute only when the household budget allows it. The value is not in pretending that every month will be identical; it is in giving the intention a visible home.
That same parent should decide in advance what “affordable” means. A custodial investment account is not a substitute for an emergency fund, rent money, or high-interest debt repayment. If the household is struggling to cover essentials, directing spare cash toward a child’s long-term account may be the wrong order of priorities. UNest can organize a goal, but it cannot make an unsuitable contribution affordable.
Another practical scenario is a relative who wants to help a child financially but does not want to manage a broad portfolio. A child-focused app may feel easier to discuss with the family because the purpose is clear. Even then, I would make sure everyone understands the account’s custodial nature and agrees on expectations before money starts moving.
How it compares with ordinary alternatives
The closest alternative is often not another investment app but a regular savings account. A bank account may feel more familiar, easier to access, and simpler to explain. It can be a better choice for money that might be needed soon or for families who value a stable cash balance over investment exposure. UNest becomes more interesting when the goal is deliberately long term and the user wants a child-specific investing framework rather than an undifferentiated savings balance.
General brokerage apps offer more flexibility and usually appeal to people who want a wider range of investment decisions. That flexibility can be useful for experienced investors, but it can also create decision fatigue. If you want to trade frequently, compare many securities, or manage several unrelated goals in one place, a general brokerage platform may suit you better than UNest.
A traditional financial adviser can provide personal guidance that an app cannot replicate. That route may be preferable when your family situation is complicated, your tax questions are significant, or you need help coordinating several accounts. UNest’s advantage is convenience and focus, not individualized financial planning.
The trade-off is therefore straightforward: UNest may be easier to approach than a full investment platform, but it is less suitable for people who want maximum control. It may feel more purposeful than a standard savings account, but it also asks you to accept the responsibilities that come with investing for a child through a custodial arrangement.
Costs deserve a close look
The app itself is free, which lowers the barrier to trying it. However, the presence of in-app purchases means “free to download” should not be interpreted as “every part of the experience has no cost.” The listed purchase range begins at $4.99 and reaches $149.99 per item. I would read each payment screen carefully and distinguish between optional app-related purchases and the money you intend to place into the child’s account.
This is one of the first questions I would answer before inviting another family member to use the app: what exactly is being paid for, when is it charged, and does it affect the investment goal or simply add a separate service? Keeping those categories separate prevents a common budgeting mistake, where the convenience cost is forgotten because the account itself was described as free.
Who will appreciate it most
UNest is a strong candidate for parents or relatives who want a dedicated, child-centered way to think about long-term saving and who prefer a guided experience over a crowded investment dashboard. It is especially suitable for someone who needs a visible reminder of the goal and wants to build a habit gradually rather than make the process feel like active market management.
The app is less convincing for a user who needs immediate access to cash, wants guaranteed returns, expects detailed professional advice, or already has a carefully managed custodial strategy elsewhere. It is also not the right first financial step for a household without a basic emergency cushion. The child-focused presentation can be motivating, but motivation should not override financial priorities.
The Everyone rating makes the app broadly approachable from a content perspective, but adults should still handle account ownership and investment decisions responsibly. A child may understand the purpose of the goal, yet that does not mean the child should be expected to interpret every financial choice. I see the app as something a parent can use to make the idea of saving tangible, not as a replacement for age-appropriate conversations about money.
What I would do before making the first contribution
I would begin by writing down the goal in plain language: what the money is for, how long I expect it to remain invested, and what amount the household can genuinely spare. Then I would review the custodial account details carefully, including who controls the account and how the arrangement fits the family’s plans.
Next, I would inspect every cost shown during setup and avoid treating an optional purchase as part of the required investment. I would also confirm that the phone is compatible, that the connection is stable, and that I have enough time to read rather than rushing through forms between errands.
After setup, I would create a simple review routine instead of checking constantly. Looking only when I have a clear reason—such as confirming a contribution, updating a goal, or reviewing the account—keeps the app in its proper role. Long-term investing is usually undermined more by impulsive reactions and neglected plans than by a lack of daily screen time.
The best way to use UNest is as a calm, dedicated planning tool, not as a shortcut to instant financial results. That mindset matches the app’s purpose and makes its focused design more useful.
My performance verdict
From a performance perspective, UNest appears well matched to its job. It is a finance app with a focused workflow, not a demanding media or gaming product, so its resource needs should generally be modest compared with heavier mobile software. The Android 7.0 minimum also makes it approachable for owners of older compatible phones, although device condition and connection quality will still affect the experience.
Its real test is not whether it can perform a dramatic number of tasks at once. The test is whether it helps a parent return to one important goal without adding confusion. On that measure, the focused child-saving concept is more valuable than a long feature list. The main friction comes from the seriousness of the account, the need to understand the custodial structure, and the need to inspect paid options carefully.
UNest holds an average rating of 3.8 from around 2.5 thousand ratings, with around 430 written reviews and over 100 thousand installs. Those figures suggest a product with an established audience, while also reminding me that it will not be a perfect fit for every family. I would recommend trying it to someone who wants a dedicated UTMA custodial account experience and is comfortable taking time to understand the financial arrangement.
My final view is positive but measured. The app makes a potentially intimidating family goal feel more concrete, and its narrow purpose can be a genuine advantage over a general brokerage platform. I would skip it if I needed cash savings, personalized advice, or advanced investment control. For a parent who wants a focused place to build a child’s long-term financial plan—and who is willing to read the details rather than tap through them—UNest is a sensible app to consider.
Frequently Asked Questions
01What is UNest: Invest & Save for Kids?
UNest is a family-focused investing and savings app designed to help parents and relatives build money for a child’s future. It typically allows adults to open and manage an investment account intended for a minor, set up recurring contributions, and invite friends or family to contribute for birthdays and other occasions. The app is aimed at long-term goals rather than everyday spending or short-term savings.
02How does investing through UNest work?
After creating an account and completing the required identity and suitability information, you choose a child, set a contribution amount, and select from the investment options available in the app. UNest then invests contributions according to the selected portfolio or strategy. Investment values can rise or fall, so returns are not guaranteed. Before depositing money, review the portfolio details, fees, risks, and withdrawal rules.
03Is UNest a 529 college savings plan or a regular bank savings account?
UNest should not automatically be treated as a traditional bank savings account or a standard 529 plan. The account type and available benefits depend on the product offered, your location, and the information shown during enrollment. Some child investment accounts may provide greater flexibility than education-only accounts, but they can also have different tax treatment and rules. Read the current account disclosures carefully before opening one.
04How much does UNest cost, and are there any additional fees?
The total cost can depend on the account plan, subscription terms, investment products, and any applicable management or fund expenses. The app may present pricing during registration, and fees can change over time. Check whether the service charges a monthly or annual fee, whether there are minimum contributions, and whether investment funds have their own expense ratios. Understanding these costs is important because fees can reduce long-term returns.
05Can I withdraw money from a UNest account whenever I want?
Withdrawal access depends on the account structure, the child’s legal ownership, and the rules that apply to the investment product. A parent or guardian may be able to request a withdrawal, but funds intended for a minor may not be as flexible as money in a personal checking account. Processing times, tax consequences, penalties, and restrictions can apply. Review UNest’s current withdrawal policy and consult a qualified financial professional if necessary.


